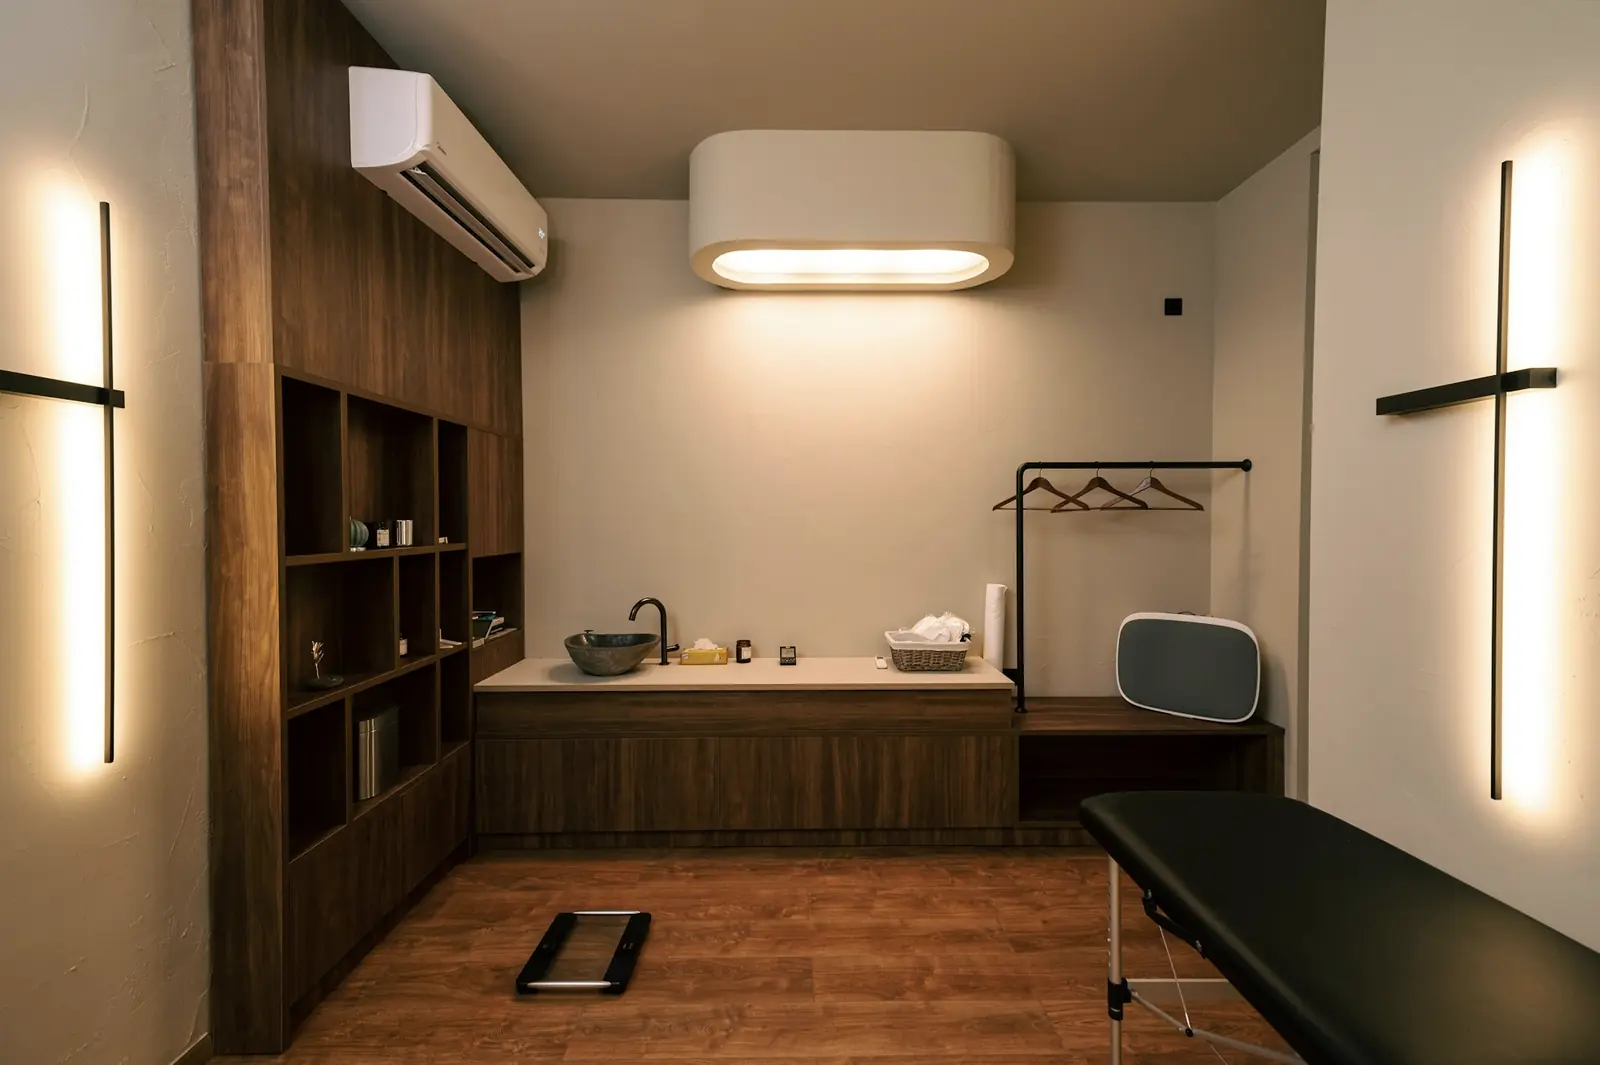
Private Healthcare Practices
Finance for Private Healthcare Practices
Growing a private practice
means investing ahead of demand.
Treatment rooms, equipment and people usually have to be in place before the patients arrive. We arrange the funding that lets you invest first.
- Confidential, no-obligation discussion
- Whole of market access
- We are a broker, not a lender
For private GPs, consultants' clinics, physiotherapy, aesthetics, dermatology, diagnostics and other private medical practices.
“He knows his stuff and is easy to deal with.”
- Lender searchWhole of marketNot tied to any one lender
- Instant QuotesNo credit searchSee indicative quotes first
- Who we helpPrivate healthcareSole traders, partnerships, LLPs and companies
- Our roleSpecialist brokerWe approach suitable lenders for you
Quick answer
What finance is available for private clinics?
Private clinics can fund expansion, medical and aesthetic equipment, treatment room fit-out, acquisitions, technology and working capital. Treatment rooms, equipment and people usually need to be in place before patients arrive, so funding lets the clinic invest first. We search the whole market for suitable lenders.
The pressures we see
What makes private healthcare different.
- Moving into larger premises as the patient base grows.
- High-value clinical and aesthetic equipment.
- Fit-outs that must meet clinical standards and feel premium.
What we can finance
Funding for private healthcare.
“Finance that appeared unattainable was sorted within a short period of time.”
- 01 Clinic Expansion Larger premises, more rooms, new sites.
- 02 Medical Equipment Diagnostic, treatment and aesthetic equipment.
- 03 Treatment Room Fit-out Clinical rooms built to standard.
- 04 Practice Acquisitions Buy an established clinic or practice.
- 05 Technology Booking, records and imaging systems.
- 06 Working Capital Launch costs and the ramp-up period.
We aren't tied to one lender or product. For every need above, we search the market for lenders who understand private healthcare.
We also arrange finance for
Private clinic funding questions answered
Can a private clinic get finance for an ultrasound, X-ray or MRI scanner?
Yes. Imaging equipment is usually funded on hire purchase or a lease, and larger systems can include installation, shielding or room works where the lender agrees. Lenders look at where referrals will come from, the clinicians and radiographers who will run and report the scans, the fee per scan against the repayment, and the resale market for the system. Professional Practice Loans, a specialist whole-of-market broker, searches lenders that fund diagnostic equipment.
Plan the regulation into the timetable. Diagnostic and screening procedures is a regulated activity under Schedule 1 of the 2014 Regulations, so a clinic in England adding imaging should check with CQC whether it needs to register or vary its registration, and X-ray and CT also bring ionising radiation rules. A scanner that cannot be used until approvals are in place still has to be paid for.
See medical equipment finance, and if the scanner needs a new room or building work, fit-out finance. You can also get instant quotes for an imaging project.
Can a private clinic borrow against money owed by insurers?
Yes. Invoice finance can advance part of the value of invoices raised to private medical insurers, embassies and corporate clients, and is repaid when they pay. Patients who pay at booking do not create invoices to fund, so it works best where insured and corporate work is a large share of income.
- The payers. Which insurers and corporate clients you bill, and how quickly each one pays.
- Rejections. How often claims are rejected or paid short, and how the shortfall is collected from the patient.
- Billing. How soon after treatment invoices go out, and who chases them.
Clinics that would rather not fund individual invoices can use a working capital facility or lock-up finance against the whole debtor book. Get instant quotes to compare options.
Ready to compare options? Get instant quotes for your clinic, or read how it works.
Acquisitions & ownership
Buying an established clinic?
An established clinic brings patients, staff and equipment, and usually a fit-out that needs updating. We help structure the purchase and the investment that follows it as one plan.
How finance works here
Invest first, then build the patient list.
Private clinics, from consultants’ rooms and diagnostics to physiotherapy, dermatology and aesthetics, usually have to invest in premises, fit-out and high-value equipment before patient numbers build. Clinical standards and patient expectations both push that investment up.
Lenders look at the clinicians’ experience and reputation, how patients reach the clinic, the mix of self-pay and insured patients, and the clinic’s regulatory registration where it applies. Established clinics with a track record find a much wider market than new ones, which rely more on the founders’ experience and contribution.
Equipment is often best funded separately through asset finance, matched to its working life, leaving term borrowing for fit-out and working capital. Our guide to hire purchase, leasing or a loan compares the options.
Preparing the case
What lenders will look at.
- Recent accounts and management figures, or a plan for a new clinic
- The clinicians’ experience and how patients are referred
- The mix of self-pay and insured income
- Regulatory registration where it applies
- Equipment quotes, fit-out costs and premises terms
We are a broker, not a lender. We help you pull this together, search the market for lenders whose criteria suit your practice and manage the process to completion. How it works →
Success stories
Funding arranged in this profession.
Specialist understanding
Finance for Private Healthcare Practices
Private healthcare finance tends to come before the revenue it creates: treatment rooms, medical equipment and people in place before patients book. Private clinic finance can fund expansion into larger premises, aesthetic and diagnostic equipment, fit-out, the acquisition of an established clinic and working capital through the launch period. Lenders consider trading history, the clinicians involved, regulatory standing and how income is earned. Whether you run a private GP service, a consultant's clinic, physiotherapy, aesthetics, dermatology or diagnostics, we search the market for lenders comfortable funding clinics through that ramp-up period, and structure loans for private practices around your plans.
Get Instant Quotes- Whole of market accessHigh street banks, specialist and private lenders.
- Specialist understandingLenders who understand how practices earn and grow.
- Your case, properly presentedStructured and put to lenders suited to it.
- With you to completionFrom the first conversation to funds arriving.
Questions
What private healthcare usually ask.
Can I get a loan to open a private clinic?
Often, yes, although new clinics are assessed more cautiously than established ones. Lenders look at your clinical experience, any existing patient base, the business plan, and how launch costs and the ramp-up period will be covered. Equipment can sometimes be funded separately through asset finance. We help present the plan and search the market for suitable lenders.
How do private clinics finance expensive medical or aesthetic equipment?
Asset finance and leasing are common, spreading the cost of lasers, imaging, diagnostic and treatment equipment over its working life. Lenders consider the equipment's resale value, the clinic's trading history and the expected income from the treatments it supports. We compare supplier finance with what is available across the market.
Can a private practice get finance for a treatment room fit-out?
Yes. Fit-out and refurbishment finance can fund clinical rooms, patient areas and the infrastructure treatments need. Because fit-out has limited resale value, lenders tend to focus on the clinic's income, trading history and lease terms rather than the works themselves. We look at the full project cost before we approach lenders.
Can I get finance to buy an established private clinic?
Yes. Buying an established clinic brings patients, staff and equipment, and lenders will look at its earnings, reliance on key clinicians, the lease and its regulatory standing, such as CQC registration where it applies. We help structure the purchase and any investment planned after it, then approach lenders suited to the deal.
Do lenders fund aesthetics clinics and physiotherapy practices?
Many do, although appetite varies between lenders and by treatment type. Lenders look at trading history, the qualifications of practitioners, the regulatory position and how income is generated. Because criteria differ so much across the market, it helps to have a broker approach lenders already comfortable with your type of practice.
How is a private clinic or physiotherapy practice valued when you buy it?
Valuations usually start from the clinic’s earnings and then look at how much of that income will transfer: patient numbers, the self-pay and insured mix, referral sources and whether the clinicians who treat the patients are staying. Lenders often expect a specialist valuation and look at the same points. See practice acquisition finance.
Do lenders fund private medical practices in London?
Yes. Lenders who fund private clinics work across the UK, including London, and assess each case on the clinicians, the income and the premises terms. You can get instant quotes to compare options for your practice.
Can a private clinic get finance for an ultrasound, X-ray or MRI scanner?
Yes. Imaging equipment is usually funded on hire purchase or a lease, sometimes with installation and room works included. Lenders look at referral sources, who will run and report the scans, the fee per scan against the repayment and resale value. See medical equipment finance.
Does a private diagnostic service need CQC registration?
In England it may. Diagnostic and screening procedures is a regulated activity under the 2014 Regulations, so a clinic adding imaging should check with CQC whether it needs to register or vary its registration, and X-ray and CT also bring ionising radiation rules. Build the approvals into the timetable before the equipment arrives.
Can a private clinic borrow against money owed by insurers?
Yes. Invoice finance can advance part of the value of invoices raised to private medical insurers, embassies and corporate clients, repaid when they pay. It works best where insured and corporate work is a large share of income. Lenders look at the payers, rejection and shortfall rates and how quickly invoices go out.
How do private clinics manage cash flow while waiting for insurers to pay?
Options include invoice finance on insurer and corporate invoices, a working capital facility, and lock-up finance against the whole debtor book. Sending invoices promptly and tracking rejected claims also shortens the wait.
Knowledge Hub
Read the guides.
Buying a Dental Practice: A Finance Guide for Buyers
A practical guide to funding a dental practice purchase: how the NHS and private income mix affects lenders, the approvals involved, and the order to put the finance together.
Read the guide →Hire Purchase, Leasing or a Loan: Financing Practice Equipment and Technology
How hire purchase, finance leases, operating leases, contract hire and loans compare for dental chairs, imaging, OCT, dispensing robots, case management systems and vehicles.
Read the guide →Let's talk
Talk it through
with a specialist.
Before you approach a lender, speak to someone who understands the transaction. Confidential, no-obligation initial discussion.
